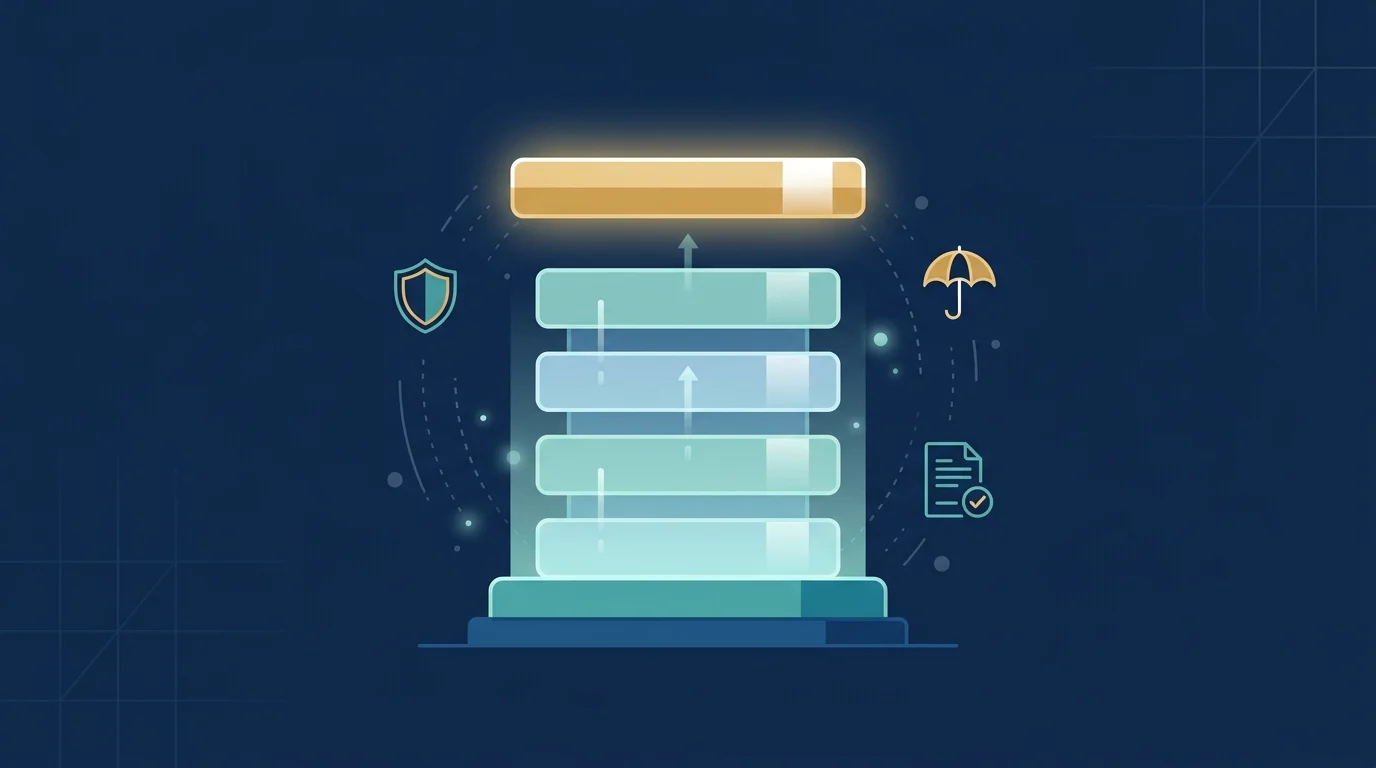
Quick Ans: In insurance, “aggregate” refers to the maximum total amount an insurer will pay for all covered claims during a policy period, usually one year. It is a cumulative cap that sits above the per-incident limit. For example, a policy might pay up to $500,000 per incident but cap total payouts at $1.5 million for the year. Once the aggregate limit is reached, no further claims are covered until the policy renews .
Insurance policies are built on limits, and few limits cause more confusion than the aggregate. Most people understand the idea of a per-incident cap: the most the insurer will pay for one accident, one lawsuit, or one medical event. But the aggregate limit operates on a different level. It asks a broader question: how much will the insurer pay in total, across every claim, before the coverage runs out for the year?
This distinction matters enormously for businesses and individuals who face the possibility of multiple claims. A single incident limit of $1 million sounds generous until a second or third claim arrives and the aggregate cap suddenly becomes the real constraint. Understanding how aggregate limits work, how they interact with per-incident limits, and where they appear across different types of insurance helps policyholders read their coverage with clear eyes.
This guide explains what aggregate means in insurance, how it differs from per-occurrence limits, and why it is one of the most important numbers in any policy.
The Core Definition of Aggregate in Insurance
An aggregate limit is the total amount an insurer will pay for all covered claims within a defined policy period . That period is typically one year, though it can vary by policy type. The aggregate is not a limit per claim. It is a limit on the sum of all claims combined.
The concept appears across multiple lines of insurance, including general liability, professional liability, health insurance, and reinsurance. In each context, the aggregate serves the same function: it caps the insurer’s total exposure for the coverage period .
Aggregate vs. Per-Incident Limit: The Key Difference
The cleanest way to understand aggregate is to place it next to the per-incident limit, also called the per-occurrence limit.
| Limit Type | What It Caps | Example |
|---|---|---|
| Per-Incident (Per-Occurrence) | The maximum paid for a single claim or event | $500,000 per incident |
| Aggregate | The maximum paid for all claims combined during the policy period | $1,500,000 total for the year |
Consider a policy with a $500,000 per-incident limit and a $1,500,000 aggregate. If the insured faces three separate claims of $500,000 each, the insurer pays all three because the total ($1.5 million) equals the aggregate. But if a fourth claim arrives, the aggregate is exhausted, and the insurer pays nothing more for the remainder of the policy period .
This is why the aggregate is often described as a cumulative cap. It does not reset with each claim. It resets only when the policy renews.
Where Aggregate Limits Appear
Aggregate limits are not confined to one corner of the insurance world. They appear in several major contexts, each with its own nuances.
General Liability and Professional Liability
Commercial general liability policies and professional liability policies commonly include both per-occurrence and aggregate limits. A business might carry a $1 million per-occurrence limit and a $2 million aggregate. The aggregate protects the insurer from an unusual cluster of claims in a single year, while the per-occurrence limit controls the size of any single payout .
Health Insurance
In health insurance, an aggregate lifetime dollar limit is a cap on the total benefits payable under a plan for a coverage unit, such as an individual or family . Regulatory rules govern how these limits can be applied, particularly regarding mental health and substance use disorder benefits, which must be treated no more restrictively than medical and surgical benefits .
Reinsurance
In reinsurance, aggregate limits serve a similar function at the insurer-to-reinsurer level. A reinsurance treaty with an aggregate limit caps the total amount the reinsurer will pay for cumulative losses over a period, often a year. This is distinct from stop-loss reinsurance, which attaches at a specific loss threshold, though both deal with cumulative exposure .
Specialty and Catastrophe Coverage
Aggregate concepts also appear in catastrophe excess of loss coverage, where losses from a single event are aggregated and treated as one occurrence for reinsurance purposes . The unifying principle is the same: multiple losses are combined and measured against a single cumulative limit.
Why Aggregate Limits Matter for Policyholders
For anyone buying insurance, the aggregate limit is not a technicality. It determines how much protection is actually available when things go wrong repeatedly.
The Risk of Exhaustion
A policyholder who focuses only on the per-incident limit may believe they have more coverage than they do. If several claims occur in one year, the aggregate can run out quickly. Once exhausted, the policy provides no further coverage until renewal. This is particularly dangerous for businesses with predictable claim patterns, such as medical practices, construction firms, and professional service providers .
Setting Realistic Limits
Understanding the aggregate helps policyholders choose appropriate limits. A business that expects one claim per year may be comfortable with a modest aggregate. A business with higher exposure to multiple claims should consider a higher aggregate, even if the per-incident limit stays the same. The aggregate is the number that reflects the total risk the insurer is willing to absorb, and it should match the policyholder’s realistic exposure.
Reading the Policy Carefully
Not every policy labels its limits clearly. Some policies have separate aggregates for different coverage parts, such as products liability versus premises liability. Others include defense costs inside or outside the limit, which affects how quickly the aggregate is consumed. Reading the declarations page and understanding how the aggregate applies to each coverage is essential.
Common Misconceptions About Aggregate Limits
Several misunderstandings surround the aggregate concept, and clearing them up prevents unpleasant surprises.
- Myth: The aggregate resets with each claim. Reality: It resets only when the policy period renews. Multiple claims in one year share the same aggregate.
- Myth: The aggregate and the per-incident limit are the same number. Reality: They are usually different. The aggregate is often a multiple of the per-incident limit.
- Myth: Aggregate limits only matter for large businesses. Reality: Any policyholder facing the possibility of multiple claims in a year should understand the aggregate, including small businesses and professionals.
- Myth: Reaching the per-incident limit means the aggregate is exhausted. Reality: A single claim can hit the per-incident limit without exhausting the aggregate, leaving room for additional claims up to the total cap.
Frequently Asked Questions About Aggregate in Insurance
What does aggregate mean in insurance?
Aggregate refers to the maximum total amount an insurer will pay for all covered claims during a policy period, typically one year. It is a cumulative cap that sits above the per-incident limit .
What is the difference between an aggregate limit and a per-occurrence limit?
A per-occurrence limit caps the payout for a single claim or incident. An aggregate limit caps the total payout for all claims combined during the policy period. The aggregate is often a multiple of the per-occurrence limit .
What happens when the aggregate limit is reached?
Once the aggregate limit is exhausted, the insurer will not pay for any additional claims during that policy period. Coverage resumes only when the policy renews, assuming the policy is renewed with a fresh aggregate .
Do all insurance policies have aggregate limits?
No. Aggregate limits are common in liability insurance, health insurance, and reinsurance, but not every policy includes one. Policies focused on a single event, such as certain property policies, may rely primarily on per-occurrence limits. Reviewing the policy declarations is the best way to confirm.
How does the aggregate limit affect my premium?
Policies with higher aggregate limits generally cost more because the insurer is accepting more total risk. The relationship between aggregate limits and premiums depends on the insurer, the line of coverage, and the policyholder’s claims history.
Conclusion
To answer the question of what aggregate means in insurance: it is the total cap on all claim payouts during a policy period, a cumulative limit that works alongside the per-incident limit to define the full scope of coverage. The per-incident limit controls the size of one claim. The aggregate controls the sum of all claims. Both numbers matter, and ignoring the aggregate can leave a policyholder exposed when multiple claims arrive in a single year. Whether you are reviewing a business liability policy, a health plan, or a reinsurance treaty, read the aggregate carefully. It tells you how much protection you truly have, and how quickly it can run out.
1 thought on “What Does “Aggregate” Mean in Insurance? A Clear Guide to Policy Limits 2026”